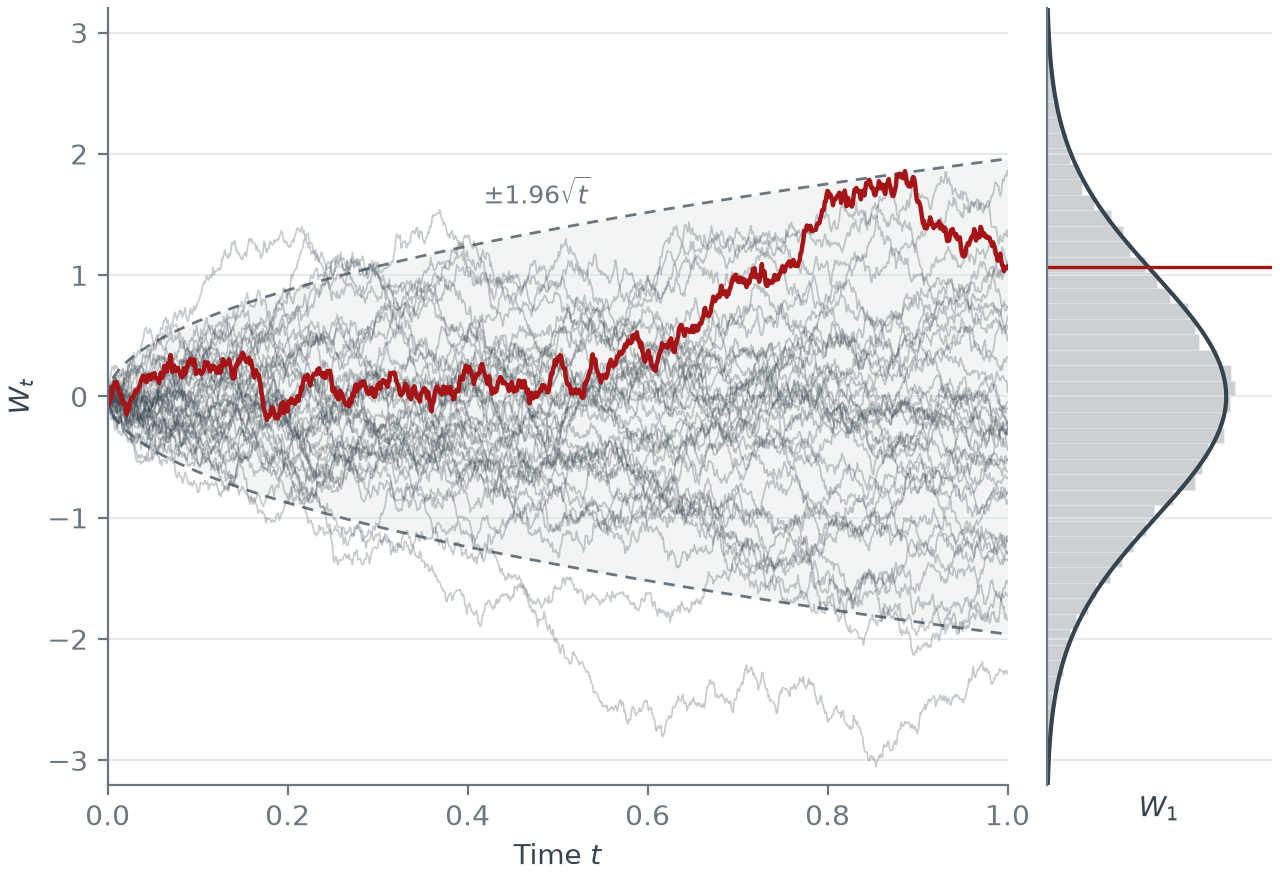
This site collects my notes on stochastic processes for finance, which I use across several courses. They start from basic probability and build up to Poisson processes, Brownian motion, Itô calculus, and the pricing of derivatives in continuous time, with and without jumps. Each step is motivated by the finance problem it will be used for.
The notes contain the full derivations and worked examples, and each chapter is available in HTML and as a PDF for printing.