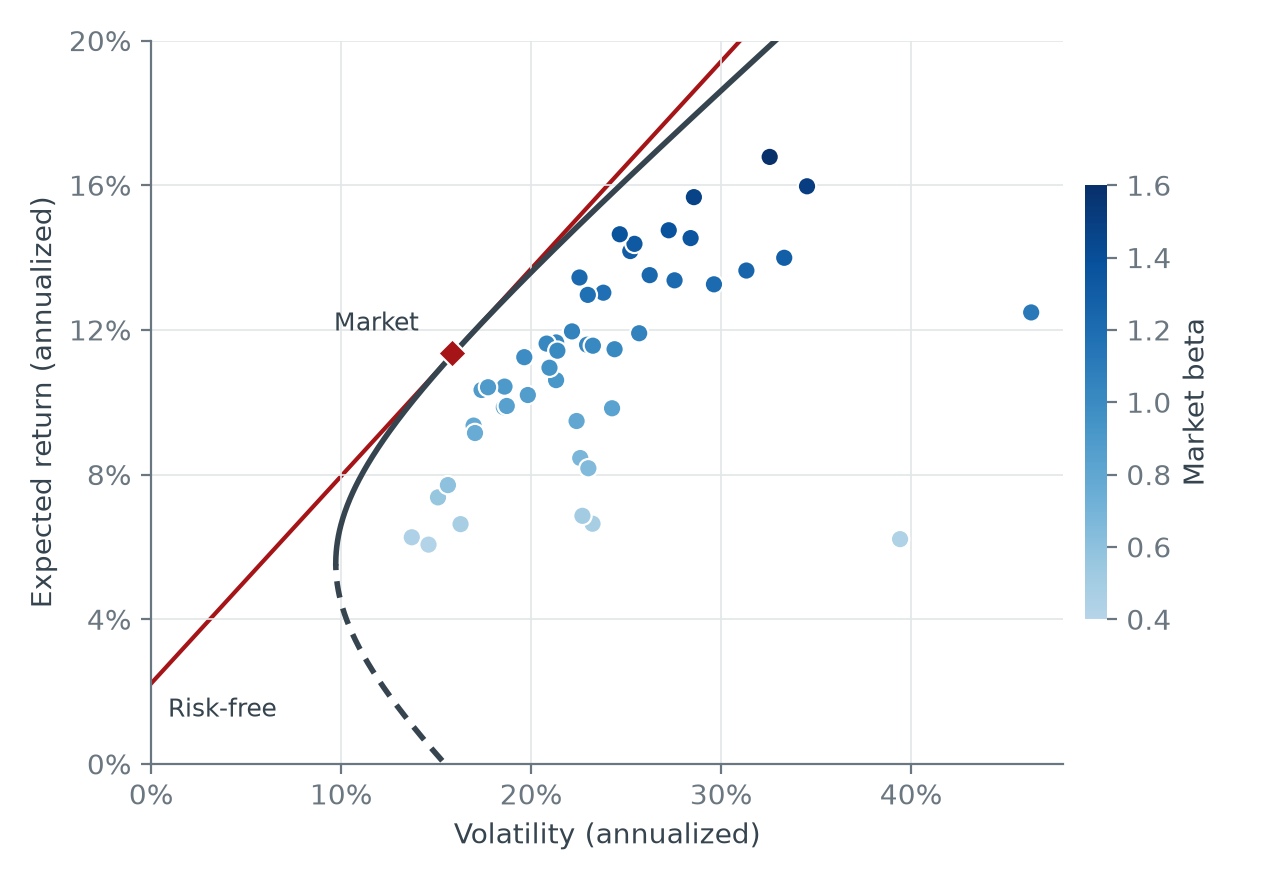
This site collects my notes and slides on investments, which I use across several courses. They start from how returns are measured and how investors trade off consumption over time, build up to mean-variance portfolio choice, beta pricing, and the CAPM, and continue with the index model, active portfolio management, and the pricing and risk management of bonds.
The notes contain the full derivations, worked examples, and a set of practice problems at the end of each chapter, and each chapter is available in HTML and as a PDF for printing. The slides follow the notes closely and complement the board in class with pictures, plots, and key equations. In the HTML version of the notes, the solution to each problem is one click away, so try the problem before expanding it.