Binomial Pricing
Options, Futures and Derivative Securities
Spring 2026
Binomial Trees
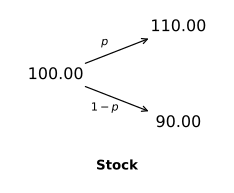
- One of the easiest ways to describe the evolution over time of a stock price is to use what in finance we call a binomial tree.
- At each point there are only two possibilities for the future stock price happening with probability p and 1 - p, respectively.
- We will see that these probabilities play no role in the price of an option.
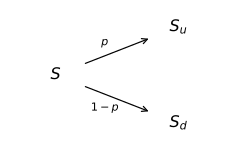
- It is useful to define S_{u} = S \times u and S_{d} = S \times d, where u and d are the gross percentage increase and decrease of the stock price over the next period, respectively.
Pricing Options
- Consider a non-dividend paying stock that currently trades for $100.
- Over the next 6-months the stock can go up or down by 10%.
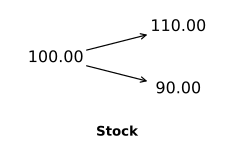
- The interest rate is 6% per year with continuous compounding.
- What should be the price of a European call option with maturity 6 months and strike price $100?
The Binomial Tree of a Bond
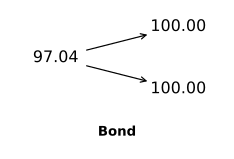
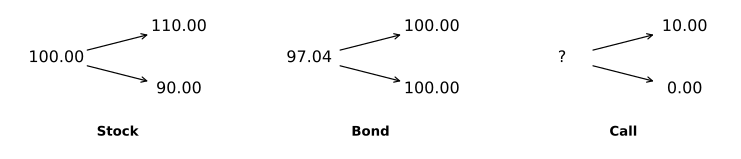
- Consider a risk-free bond with maturity 6 months and face value equal to the strike price of the call, i.e., $100.
- The price of the bond is: Z = 100 e^{-0.06 \times 6/12} = \$97.04
- The binomial tree for the bond is:
The Replicating Portfolio Approach
- We will price the option by using the stock and bonds to replicate the payoffs of the call.
Call Leverage
- The replication analysis reveals that the call can be seen as a levered position on the stock.
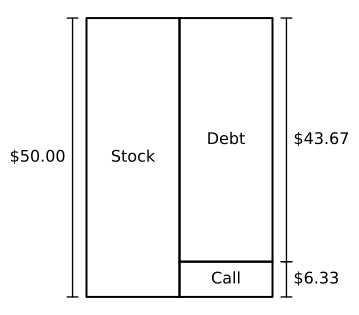
- A 1% fall in the stock reduces the call by about 0.5/6.33 = 7.9\%.
Replicating a Put Option
- Consider now a European put option with the same maturity and strike price as the call.
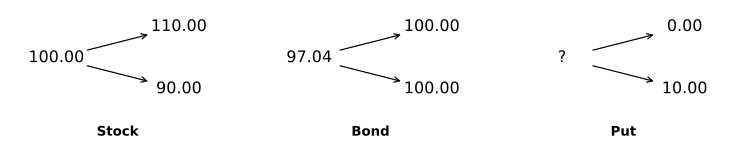
- As before, we replicate the payoffs of the put option by trading the stock and the bond: \begin{align*} 110 N_S + 100 N_Z & = 0 \\ 90N_S + 100 N_Z & = 10 \end{align*}
Put Leverage
- Where the call is a levered long position in the stock, the put is an investment in the risk-free bond financed in part by shorting stocks.
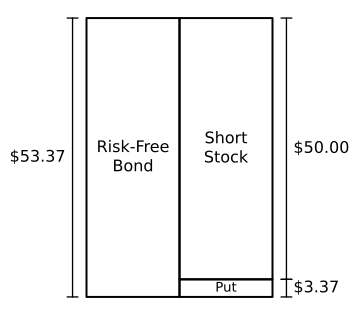
- A 1% rise in the stock reduces the put by about 0.5/3.37 = 14.8\%.
Replicating A Generic Derivative
- The analysis so far suggests that we can generalize the replicating approach to price any derivative.
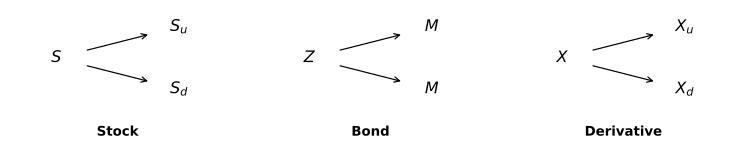
- The bond has face value M and price Z = M e^{-r T}.
- As before, we start by replicating the payoffs of the derivative by trading the stock and the bond: \begin{align*} S_{u} N_{S} + M N_{Z} & = X_{u} \\ S_{d} N_{S} + M N_{Z} & = X_{d} \end{align*}
State Prices
- The risk-neutral probabilities are intimately related to the so-called Arrow-Debreu securities depicted below.
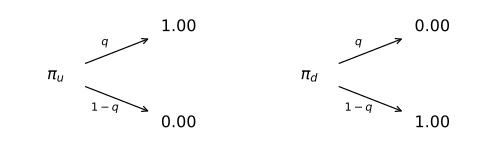
- The price of each security is then the expected payoff using the risk-neutral probabilities, discounted at the risk-free rate: \begin{align*} \pi_{u} & = (1 q + 0 (1 - q)) e^{-r T} \\ \pi_{d} & = (0 q + 1 (1 - q)) e^{-r T} \end{align*}